Business Loans for Bad Credit: How to Get Funded When Your Credit Isn't Perfect
Credit score feeling a little stormy?
Need working capital, equipment, inventory, or breathing room, but your credit history is less than perfect?
You may still have options.
Business loans for bad credit can help qualified owners access funding by looking beyond a score. Lenders may also review:
- Business revenue
- Cash flow
- Time in business
- Bank activity
- Outstanding invoices
- Equipment or other collateral
- Your plan for using the funds
The key? Choose the right product, prepare a clear application, and understand the full cost before signing.
Keep momentum moving
Your credit score isn't your ceiling.
Qualify with as little as 4 months in business and no minimum FICO — compare offers from top financing partners and pick the terms that fit.
See My Real OptionsExplore business financing options with FMC
Can you get a business loan with bad credit?
Yes: depending on your complete financial profile.
Traditional banks often place heavy weight on personal credit, long operating histories, and detailed financial statements. Alternative financing providers may take a broader view.
That can create more flexibility for owners with:
- Low or fair personal credit
- Limited business credit history
- A newer business
- Previous financial setbacks
- Uneven: but improving: cash flow
FMC offers financing options for diverse credit profiles. Some businesses may qualify with as little as four months in business, depending on the product and other eligibility factors.
There is no guarantee of approval. Terms, rates, funding amounts, and repayment structures vary. But imperfect credit does not automatically close the door.
What lenders look at beyond your credit score
Your credit score is one puzzle piece: not the whole whimsical puzzle.
Lenders may review:
1. Consistent revenue
Steady deposits can demonstrate repayment ability. Strong revenue may help offset a weaker credit profile.
Be ready to show:
- Monthly sales
- Recent business bank statements
- Payment processor reports
- Accounts receivable
- Seasonal revenue patterns
2. Time in business
A longer operating history can help establish stability. However, some financing programs consider businesses with only a few months of history.
FMC may work with businesses that have been operating for as little as four months, depending on the application.
3. Cash flow
Revenue looks at what comes in. Cash flow shows what remains after expenses.
Lenders may consider:
- Payroll
- Rent
- Inventory
- Taxes
- Existing debt payments
- Overdrafts or returned payments
- Average account balances
Keep your business banking tidy. Clean statements make a brighter impression.
4. Business purpose
Explain exactly how you will use the funding.
Strong examples include:
- Purchasing revenue-generating equipment
- Buying inventory for confirmed demand
- Covering a temporary cash-flow gap
- Hiring staff for a profitable contract
- Repairing a vehicle or essential machine
- Funding a purchase order
- Expanding into a proven market
A clear purpose helps connect the funding to future repayment.

Types of business loans for bad credit
Different financing products look at different strengths. Match the funding to the moment.
Working capital
Need flexible funds for everyday expenses?
Working capital can help cover:
- Payroll
- Rent
- Marketing
- Supplies
- Utilities
- Short-term operating needs
It can be useful when the business is healthy but timing feels awkward and cash is temporarily shy.
Business lines of credit
A line of credit provides access to a revolving pool of funds.
You draw what you need, repay it, and potentially draw again.
Consider it for:
- Seasonal expenses
- Emergency repairs
- Inventory purchases
- Short-term gaps between invoices and payments
Equipment financing
Need a vehicle, machine, medical device, or technology upgrade?
Equipment financing uses the asset being purchased as part of the financing structure. This may make it a practical option for owners with imperfect credit.
Accounts receivable financing and factoring
Waiting on unpaid invoices can make a healthy business feel strangely cash-starved.
Accounts receivable financing or factoring may help convert eligible invoices into working capital sooner. Approval may focus more on the quality of your customers and invoices than on your personal credit alone.
Purchase order financing
Have a confirmed order but not enough cash to fulfill it?
Purchase order financing may help fund the inventory or production needed to complete the sale.
Inventory financing
Inventory financing can help you purchase products before a busy season, fulfill demand, or keep shelves from looking a little too lonely.
Term loans
A term loan provides a lump sum with scheduled repayments.
It may work for:
- Expansion
- Renovations
- Consolidated business projects
- Large equipment purchases
- Planned growth initiatives
FMC’s financing options also include SBA loans, commercial real estate financing, residential investment property loans, and more.
How FMC helps simplify the process
Bad-credit financing can feel foggy. FMC’s process is designed to make the path clearer.
Diverse credit profiles welcome
FMC considers more than a perfect credit score. Financing options may be available for owners with varied credit backgrounds.
Four months may be enough to begin
Some products may be available to businesses with as little as four months of operating history.
That can matter for newer businesses that are growing quickly but have not yet built a long credit profile.
Same-day funding potential
Time matters when payroll, inventory, or a high-value opportunity is waiting.
FMC’s fintech-driven underwriting process can move quickly, with funding potentially available the same day for qualified applicants and approved offers.
Transparent underwriting through ROK Intelligence
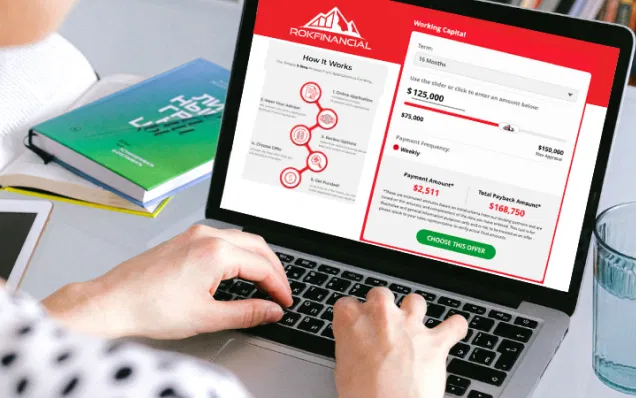
ROK Intelligence helps streamline the funding process by evaluating business information efficiently.
The offer calculator helps show important details, including:
- Funding amount
- Payment frequency
- Estimated payment amount
- Total repayment information
- Available terms
No sparkly mystery box. No surprise-heavy guessing game. Review the offer carefully and choose what fits.
Check your potential financing options
How to improve your approval chances
Ready to make your application stronger?
Take these practical steps.
Clean up your financial records
Gather:
- Recent business bank statements
- Business and personal tax returns
- Profit-and-loss statements
- Balance sheets
- Accounts receivable reports
- Business registration documents
- Business licenses
- Proof of ownership
- Government-issued identification
Organized documents can help reduce delays.
Separate business and personal finances
Use a dedicated business bank account whenever possible.
This helps lenders understand:
- What belongs to the business
- How much revenue is coming in
- Which expenses are operational
- Whether cash flow is stable
Reduce overdrafts and returned payments
Review your recent statements before applying.
If possible:
- Avoid negative balances
- Keep a cushion in the account
- Schedule recurring payments carefully
- Resolve unpaid obligations
- Monitor daily cash flow
Explain past credit issues
A short, direct explanation can add useful context.
Was the issue caused by:
- A temporary downturn?
- A medical or personal emergency?
- A failed business venture?
- A customer who paid late?
- A major equipment breakdown?
Focus on what changed and how the business is performing now.
Borrow for a productive purpose
Use financing for a specific business need: not vague financial wandering.
Before accepting an offer, ask:
- Will this funding create or protect revenue?
- Can the business handle the payment schedule?
- What happens during a slow month?
- Does the repayment frequency match cash flow?
- Is the total cost reasonable for the expected return?

Read the offer before you celebrate
Fast funding is exciting. A fast decision without careful review? Less delightful.
Compare:
- Total repayment amount
- Annual percentage rate, when available
- Factor rate, if applicable
- Origination fees
- Late or returned-payment fees
- Prepayment terms
- Repayment frequency
- Personal guarantee requirements
- Collateral or UCC filing requirements
Some alternative financing products use factor rates instead of traditional interest rates. Ask how much you will repay in total.
Also stress-test the payment:
- What if sales drop 20%?
- What if a customer pays late?
- What if equipment needs repair?
- Can you still cover payroll and taxes?
If the payment leaves no breathing room, the offer may not be the right fit.
What if you do not qualify?
Do not panic. Try a calmer, more strategic route.
Consider:
- Applying for a smaller amount
- Choosing secured equipment financing
- Exploring invoice factoring
- Building business credit
- Paying down revolving debt
- Correcting errors on your credit reports
- Working with a community lender or CDFI
- Waiting for several months of stronger bank activity
- Reapplying with updated financial records
For government-backed possibilities, review the U.S. Small Business Administration loan programs. SBA eligibility depends on the program and lender, and approval is not automatic.
A simple path forward
Ready to move from worried to wonderfully organized?
- Check your personal and business credit.
- Identify the exact amount you need.
- Define how the funds will support revenue or stability.
- Gather your financial documents.
- Compare financing products: not just lenders.
- Review total repayment and payment timing.
- Apply for an option that matches your cash flow.
- Use the funding carefully and monitor results.
Your credit history is part of your story. It does not have to be the final chapter.
With flexible financing options, transparent terms, and fast technology-driven underwriting, FMC can help you explore a practical next step: even when your credit is not perfect.
Start exploring business loans for bad credit with FMC
This article is for general informational purposes only and is not financial, legal, tax, or accounting advice. Financing approval, rates, terms, and funding speed depend on lender review, business qualifications, and other factors. Review all offer documents carefully and consult a qualified professional before making financing decisions.
For a closer comparison before you apply, read merchant cash advance, same day business fundingand working capital loans.
Keep exploring